UK house price growth halves as Middle East conflict deters buyers
Annual house price growth in the UK slowed to 0.8% in September, down from 1.6% in August, as Middle East conflict fanned inflation concerns and pushed mortgage rates higher, Nationwide said.
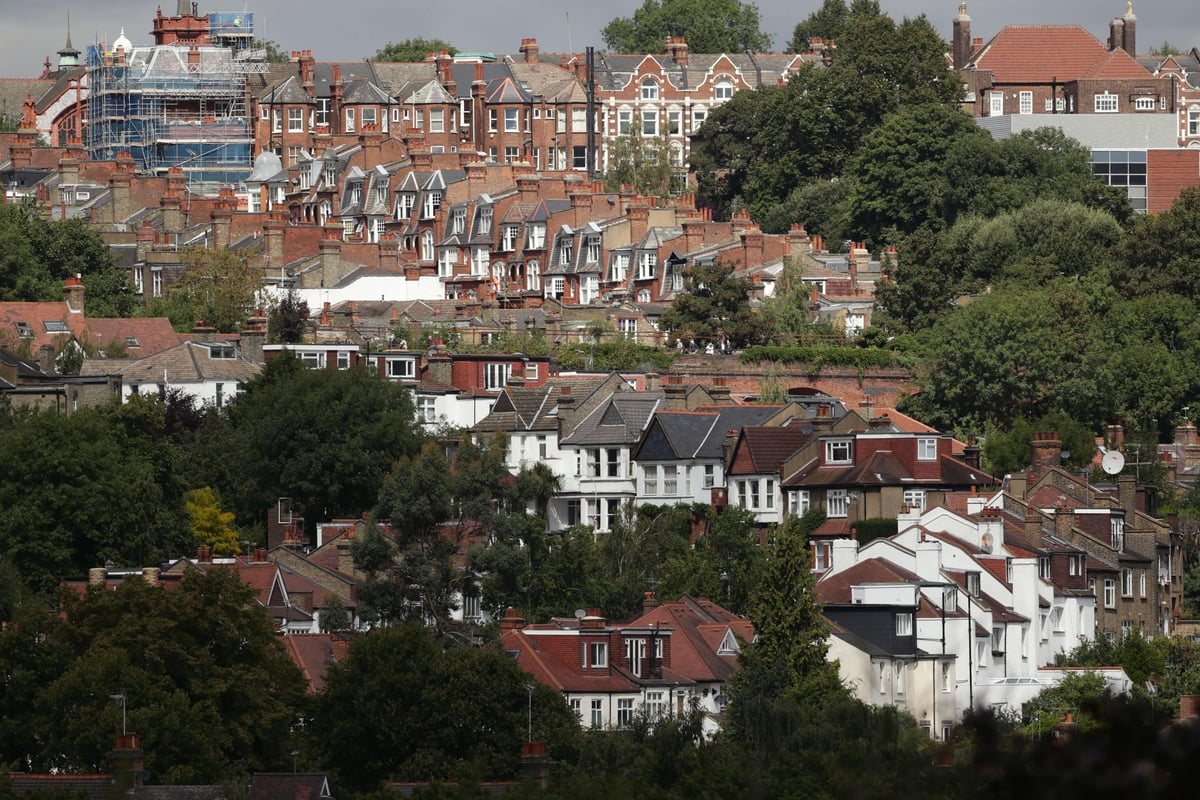
Annual house price growth in the UK halved last month, as economic uncertainty sparked by conflict in the Middle East continued to deter homebuyers and rising mortgage interest rates weighed on the market. The average price of a British home rose 0.8% in the year to September to £274,251, according to Nationwide building society. That was half the 1.6% rate recorded in August and marked the slowest pace of annual house price growth since December last year.
On a monthly basis, prices fell by 0.2% in September, the lender said, underscoring the loss of momentum in a market that had shown signs of stabilisation earlier in the year. The slowdown reflects a combination of affordability pressures and a deterioration in consumer confidence, with the conflict in the Middle East fanning concerns around inflation, Nationwide added.
The building society said the conflict has heightened fears that energy costs and wider prices could rise again, complicating the outlook for interest rates. Mortgage lenders have responded by repricing home loan products, pushing up borrowing costs for prospective buyers and those coming to the end of fixed-rate deals. Higher mortgage rates directly reduce the amount households can borrow and stretch affordability further, particularly for first-time buyers who are already grappling with elevated deposit requirements.
Nationwide’s figures suggest that the housing market is entering a more subdued phase after a period of modest recovery. The annual growth rate of 0.8% is the weakest since December, when the market was still adjusting to the aftermath of previous rate increases. The monthly decline of 0.2% indicates that prices are now edging lower rather than merely rising more slowly, a shift that could have broader implications for household wealth and consumer spending.
Economists note that the housing market is highly sensitive to expectations about the Bank of England’s interest rate path. While inflation has eased from its peak, the conflict in the Middle East has introduced a new source of uncertainty, raising the prospect that the central bank may keep rates higher for longer than previously anticipated. That prospect has already been reflected in swap rates, which underpin fixed-rate mortgage pricing, and lenders have begun to adjust their offerings accordingly.
The slowdown in house price growth may also affect the wider economy. Housing is a key component of household wealth in the UK, and a weaker market can dampen consumer confidence and spending. For those looking to move or remortgage, the combination of slower price growth and higher borrowing costs creates a challenging environment. Sellers may need to adjust their expectations, while buyers could find that their purchasing power has been eroded.
Nationwide’s report comes amid a broader debate about the resilience of the UK economy. While employment remains relatively strong and wages are rising, the cost-of-living squeeze continues to weigh on many households. The housing market is often seen as a bellwether for consumer sentiment, and the latest data suggest that caution is prevailing.
The building society’s figures are based on its own mortgage lending data and are widely watched as an early indicator of housing market trends. Other indices, including those from Halifax and the Office for National Statistics, will provide further clues in the coming weeks. For now, the picture is one of a market that is losing steam, with annual growth at its weakest in nine months and monthly prices falling.
Analysts will be watching closely to see whether the slowdown deepens in the final quarter of the year. Much will depend on the trajectory of the conflict in the Middle East, the path of inflation, and the Bank of England’s next moves on interest rates. With mortgage rates expected to remain elevated for some time, the pressure on buyers and sellers alike is unlikely to ease soon.
5