John Healey Poised to Raise Bank Taxes in 28 October Budget
Chancellor John Healey is preparing to tax Britain's banks in his first budget on 28 October to offset damage to public finances from war in the Middle East, with unions urging a raid of at least £9 billion on the City.
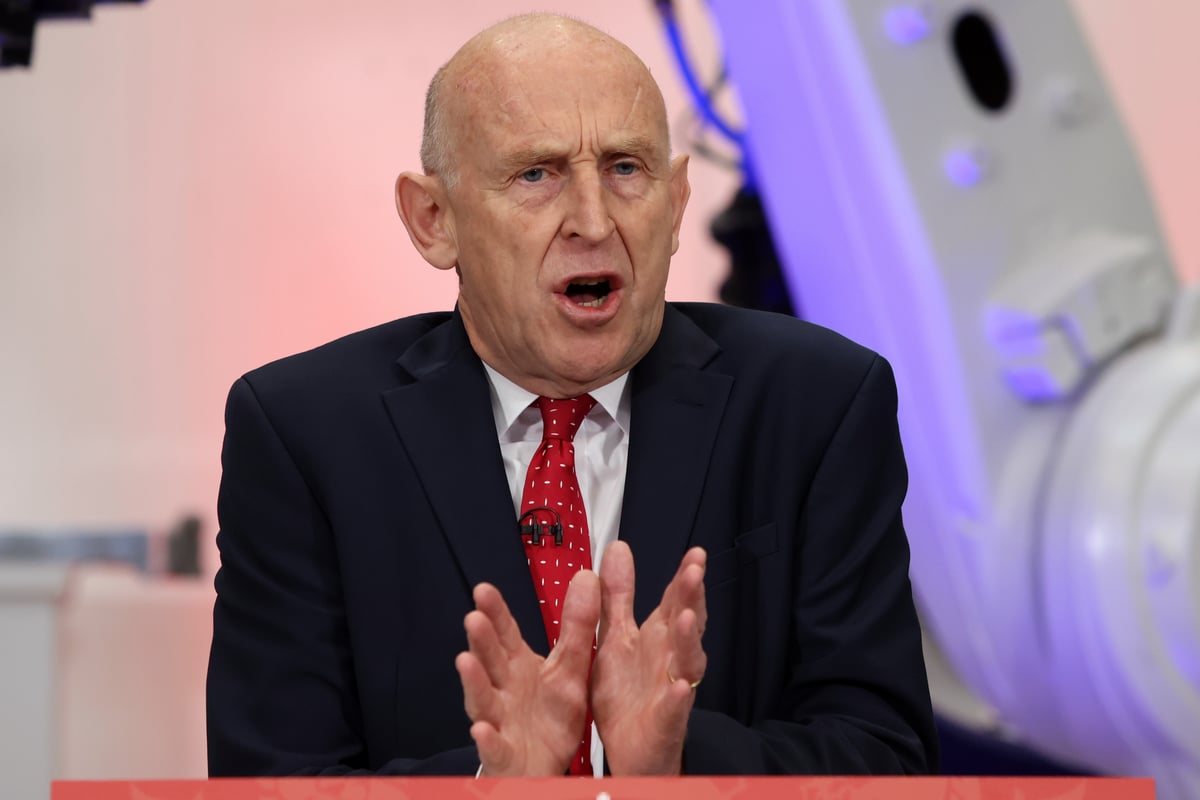
Chancellor John Healey is poised to raise taxes on Britain's banks in his first budget on 28 October, as the Treasury seeks to offset the damage inflicted on the public finances by war in the Middle East. The move would target a sector already bracing for higher levies, according to people familiar with the government's plans.
The chancellor is currently in Bangkok, where the International Monetary Fund has praised the UK's progress towards balancing the books and urged him to «stay the course». That endorsement from the IMF gives Healey political cover to press ahead with a tax raid that is likely to be contested by the banking industry.
Unions have added pressure on the chancellor to go further, calling for a budget tax raid of at least £9 billion on banks. The demand underscores the political appetite for extracting more revenue from the financial sector at a time when the public finances are under strain from overseas military commitments.
Banks in the Square Mile are braced for higher levies in what is expected to be a new Treasury tax grab. The City of London, a key contributor to UK tax receipts, has long been a target for governments seeking to shore up revenue without raising headline rates on households.
The timing of the budget places the banking sector at the centre of the government's fiscal strategy. With the war in the Middle East continuing to weigh on economic forecasts and public borrowing, the chancellor faces limited options for closing the gap between spending and revenue.
Healey's decision to target banks reflects a broader calculation that the sector can absorb higher taxes without derailing lending or investment. However, industry figures are likely to warn that repeated levies could undermine the UK's competitiveness as a global financial centre.
The IMF's praise for the UK's fiscal progress, delivered while Healey was in Bangkok, signals that international institutions are watching the budget closely. The fund's call to «stay the course» suggests it views the government's consolidation plans as credible, even as it acknowledges the pressure from geopolitical shocks.
For the banking sector, the budget represents the latest in a series of fiscal interventions that have reshaped the tax landscape since the financial crisis. Lenders have already faced surcharges and levies in previous budgets, and the prospect of further increases will feed into their planning for the coming year.
The chancellor's first budget is expected to set the tone for the government's economic approach, balancing the need for revenue against the risk of stifling growth. How far he goes on bank taxes will be read as a signal of his willingness to confront powerful interests in the City.
With the budget date set for 28 October, the coming weeks will see intense lobbying from both unions and the banking industry. The outcome will shape not only the government's fiscal position but also its relationship with a sector that remains central to the UK economy.
7