Average Five-Year Fixed Mortgage Rate Hits 6% for First Time in Three Years
The average five-year fixed-rate mortgage in the UK has reached 6.00%, its highest level since September 2023, as turmoil in bond markets pushes up lenders' funding costs and fuels expectations of a base rate rise. The average two-year fixed rate is close behind at 5.98%.
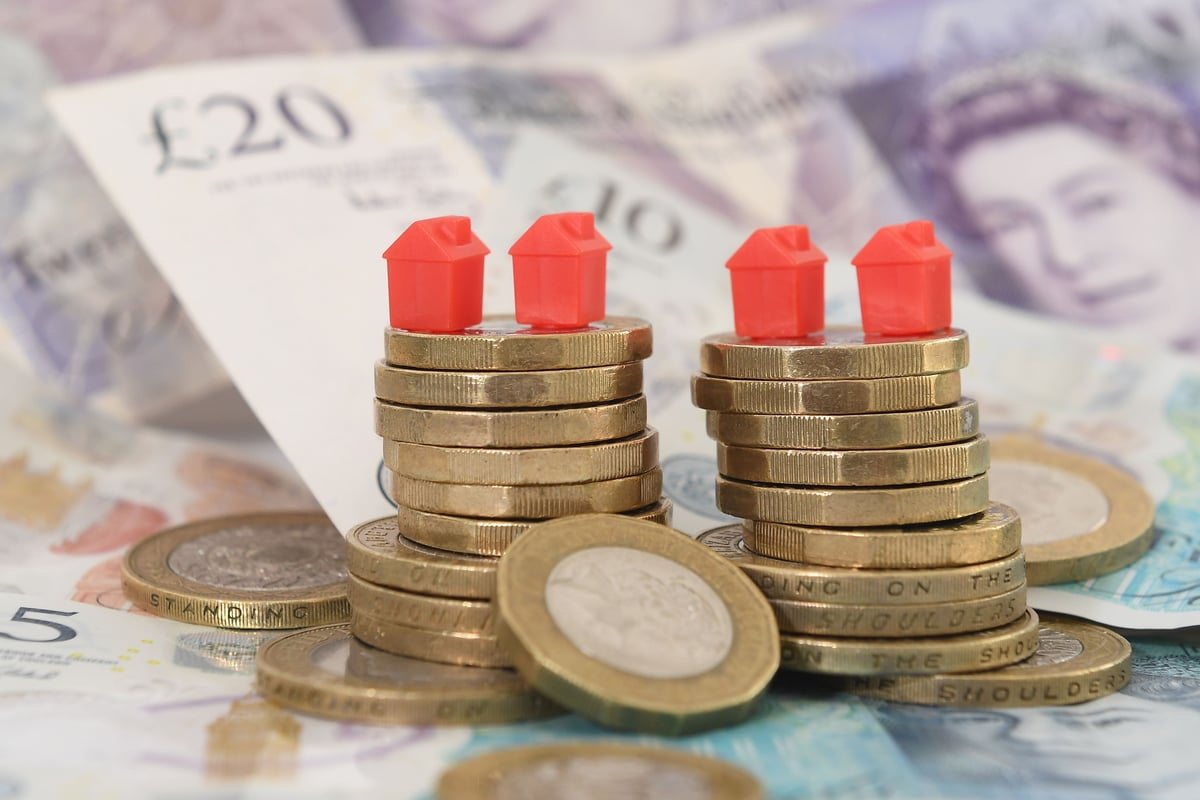
The average cost of a five-year fixed-rate mortgage in the UK has climbed to 6.00%, the highest level in three years, as turbulence in the bond markets drives up the price lenders pay to fund home loans. Figures from financial information provider Moneyfacts show the average five-year fix has not been this expensive since September 2023, while the average two-year fixed rate stands just below the threshold at 5.98%, its highest point since December of that year.
Banks and building societies have been raising their mortgage prices in response to conditions in the money markets, where expectations of a further increase in the Bank of England's base rate have hardened. When bond yields rise, the cost of wholesale funding for lenders increases, and those higher costs are typically passed on to borrowers through more expensive fixed-rate deals. The shift marks a significant reversal for homeowners and prospective buyers who had grown accustomed to a period of relative stability in mortgage pricing.
The 6% milestone carries symbolic weight as well as practical consequences. For borrowers, it means monthly repayments on new fixed-rate deals are materially higher than they were when rates were lower, squeezing household budgets already under pressure from the broader cost of living. For those coming to the end of an existing fixed-rate deal, the jump from rates secured several years ago could be substantial, prompting many to reconsider their options or seek advice from brokers.
The two-year fixed rate, now at 5.98%, is closely tracking the five-year average, reflecting a market in which lenders are repricing across the board rather than adjusting specific products. The narrow gap between the two rates suggests that expectations of near-term rate movements are influencing pricing at both ends of the fixed-rate spectrum. Moneyfacts data is widely used as a benchmark for the mortgage market, and the latest figures confirm that the era of ultra-low borrowing costs remains firmly in the past.
The development will add to the financial pressure on households across the country, particularly first-time buyers who are already grappling with high property prices and strict affordability checks. Lenders assess borrowers' ability to repay against stressed interest rates, meaning that higher market rates can reduce the amount people are able to borrow, further limiting access to home ownership. For existing homeowners, the prospect of refinancing at a higher rate may lead to difficult decisions about whether to fix now, choose a variable product, or delay moving.
Analysts will be watching the bond markets closely in the coming weeks for signs of whether the upward pressure on mortgage rates will persist or ease. Much depends on the trajectory of inflation and the Bank of England's next decisions on interest rates, which in turn shape the cost of funding for lenders. Until there is greater clarity, borrowers are likely to face an environment in which mortgage pricing remains elevated and volatile, with the 6% average serving as a stark reminder of how quickly the cost of borrowing can change.
5